 : +1 308-7304-232
 : +44 (744)-139-7094
 : +61 4 8080-3582
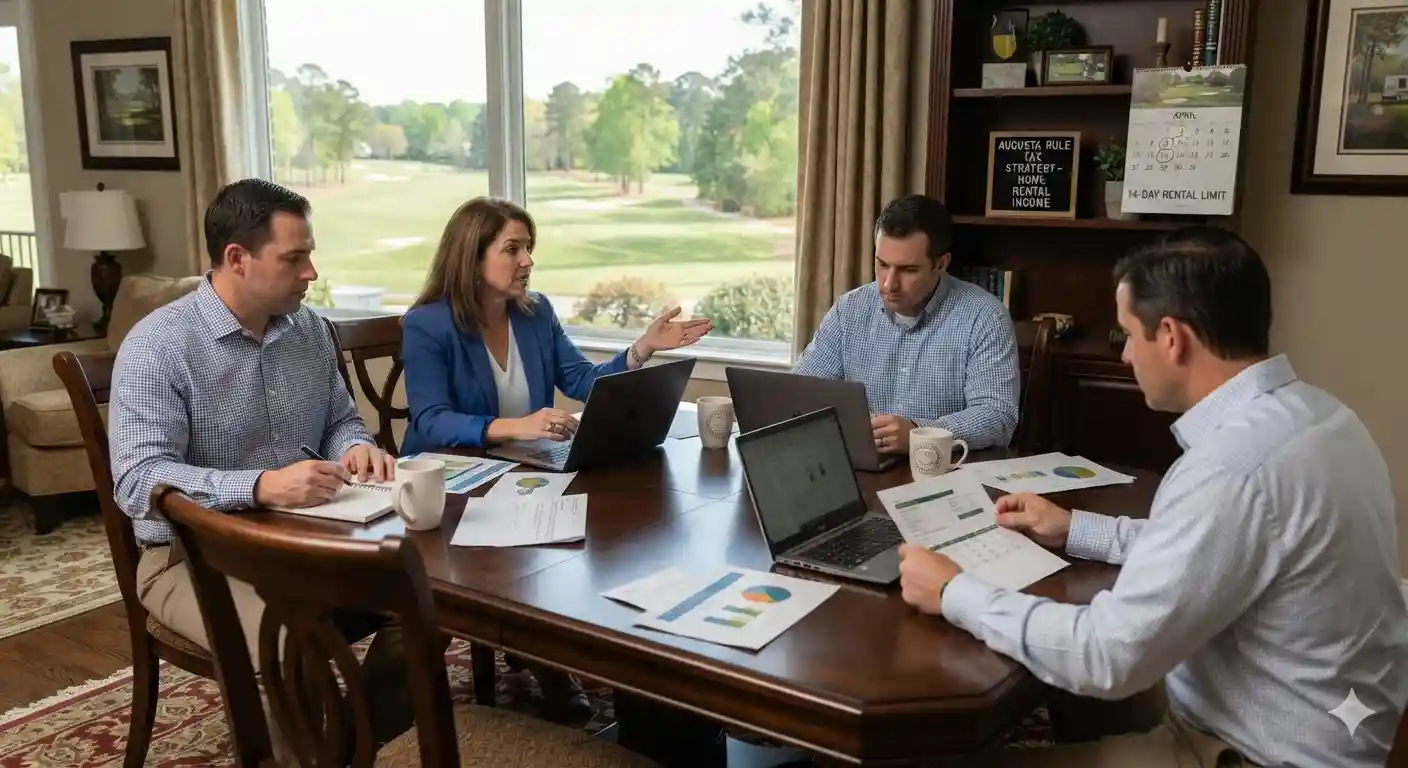
The Augusta Rule: How to Turn Your Home Into a Tax-Free Income Source
Imagine a strategy baked directly into the Internal Revenue Code which enables you to generate thousands of dollars of personal income completely tax free, while at the same time giving you a huge tax deduction for your business. That's not some aggressive loophole or an unvouched "tax hack" at all. That's the Augusta Rule, a perfectly legitimate tax strategy.
Codified under IRC Section 280A(g), the Augusta Rule is one of the most potent and underused wealth preservation tools available to US homeowners and entrepreneurs.
What is the Augusta Rule?
The Augusta Rule (IRC Section 280A(g)) provides that if a taxpayer uses a dwelling unit as their personal residence and rents it out for 14 days or fewer during the calendar year, the rental income is 100% excluded from federal gross income.
The Core Mechanics
Tax free personal income: you don't report the rental income on your personal federal tax return (Form 1040). It completely bypasses Schedule E.
No impact on AGI. As it's excluded from your gross income it won't increase your Adjusted Gross Income (AGI) and so won't push you into a higher tax bracket or trigger the Net Investment Income Tax (NIIT).
No deductions allowed. The other side of that rule is that you can't deduct any of the expenses (cleaning, maintenance, rental depreciation etc.) that relate to that 14 day rental period.
The Fascinating History
It got its nickname from the city of Augusta, Georgia (home of the Masters golf tournament). In the 1970s residents of Augusta lobbied Congress to allow them to rent out their homes to Masters spectators and golfers for the week of the tournament without having to pay income tax.
Congress put the exemption in place in the Tax Reform Act of 1976 and crucially made it a nationwide law. You don't have to live near a golf course to qualify for it; it's a nationwide law for qualifying homeowners.
Who is eligible for the Augusta rule?
To qualify for this tax exemption legally you must meet the IRS definitions of the type of property and the type of ownership.
Property Requirements
The property must be a "dwelling unit" which is used by the taxpayer as a residence. That would include:
- Primary residences
- Secondary homes or vacation properties
- Apartments, condominiums, and mobile homes
- Yachts or houseboats (provided they have sleeping, cooking, and toilet facilities)
Note: You can't use the rule for a property that is used entirely as a rental property as it must be your principal residence during the tax year.
Entity Requirements: Who is paying the rent?
You can of course rent your property out to an external third party (e.g. to tourists during a local festival). The most profitable use of the arrangement is for business owners who rent their property out to their own company. Whether you're eligible for that though is going to be down to your business structure.
| Entity Type | Can You Use the Augusta Rule? | Rationale |
| S-Corporation | YES | Legally separate taxpayer from you personally. |
| C-Corporation | YES | Legally separate corporate taxpayer entity. |
| Partnership / Multi-Member LLC | YES | Functions as a distinct entity filing separate returns. |
| Sole Proprietorship | NO | No legal separation; you cannot legally rent to yourself. |
| Single-Member LLC (Disregarded) | NO | Treated as a sole proprietorship for tax purposes. |
The Business Strategy: Double-Dipping Legally
For an eligible business owner (i.e. an S-Corp shareholder) the Augusta Rule is a financial planning event of a most extraordinary nature:
The business deduction: your company holds its quarterly board meetings, executive retreats or team planning sessions at your home. The business pays you a reasonable rental rate and can deduct 100% of that cost as an ordinary and necessary business expense under IRC section 162.
The personal exclusion: you receive the money personally and pay 0% federal income tax on it under section 280A(g).
Example Scenario
Let's look at the financial math of a hypothetical business owner who utilizes the maximum 14 days:
If the actual FMV of your home as a meeting space is $1,500 per day and you're renting it to your S-Corp for 14 days, the company will write a $21,000 check.
Your S-Corp will reduce its taxable net income by $21,000.
You pocket the $21,000 completely tax free.
Assuming a 32% marginal tax bracket this one strategy saves you $6,720 in cash taxes and safely moves capital from your business account into your personal pocket without any payroll or self-employment taxes.
Legitimate business uses for your home
You can't just write a corporate check to yourself on a Tuesday. There has to be a genuine business purpose for the rental of the venue. Qualifying events would be:
Quarterly Board meetings: review of the company's financials, updates and corporate resolutions.
Annual Strategic Planning: setting the multi-month KPIs and goals.
Team building & training days: running employee workshops and/or continuing education sessions.
Client Appreciation Events (hosting a dinner or presentation for key accounts).
Shareholder/Investor Updates: Updating stakeholders on the pitch.
The Hard Limits and Strict IRS Rules
As this is such a profitable strategy the IRS will be looking very closely at any transactions between the business owner and their personal residence. To ensure your deduction survives an audit you have to adhere to three absolute rules:
Rule 1: The 14-Day Cliff
The 14 day rule is a hard cap not a sliding scale. If you let the property for 14 days the income is tax free. If you let it for 15 days the entire exclusion is gone. All 15 days of rental income are fully taxable from the very first dollar.
Rule 2: Fair Market Value (FMV) Capping
You can't just arbitrarily charge your company $5k a day for a standard living room. The rent has to be what a local commercial venue (a boutique hotel conference room, a local co-working meeting room etc) would charge for that many people.
⚠️ The Sinopoli precedent: In the classic tax court case of Sinopoli v. Commissioner, a group of doctors took a large number of deductions for the rental of their homes to their business. They had no market data to justify the high prices they were charging so the Tax Court reduced their deductions to a mere $500 per meeting and effectively wiped out $290,900 of the deductions as being completely unsupported.
Rule 3: Corporate Separation
The company have to actually pay you. The money has to come out of the business account (by way of cheque or bank transfer) and go directly into your personal account. You cannot simply use a series of bookkeeping journal entries to "offset" the balance. A clean cash trail is essential.
Your Audit Proof Checklist (The Documentation Trail)
Your Augusta Rule deduction is entirely dependent on your documentation. If you're ever audited you must be able to produce a clean contemporaneous record of the event. Use this exact sequence to protect your deduction:
- Draft a formal rental agreement (a standard short term lease) between you (the landlord) and your company (the tenant) setting out the exact dates, times and costs.
- Gather local commercial comparables (comps) i.e. print out or PDF the quotes you've received from local hotels, meeting spaces and event venues of a similar size and specification to support your daily rate. Keep that in your corporate tax folder.
- Issue a formal corporate agenda. That's exactly what was covered in the time of the meeting.
- Take detailed corporate minutes: record the minutes of the meeting, the list of attendees and the resolutions passed (signed) at the meeting.
- Issue a corporate invoice and a receipt. The invoice should be issued in your name and the company must issue a formal payment which exactly matches that invoice.
You're moving from an ad hoc tax game to a fully defensible, compliant corporate action. As always you should talk to a qualified CPA or tax advisor to ensure the Augusta Rule is applied in the correct way to your particular corporate structure and in accordance with your state's rules.
Ready to Scale Your Business?
Connect with our experts to learn how our outsourcing solutions can drive growth.
BOOK A DISCOVERY CALL